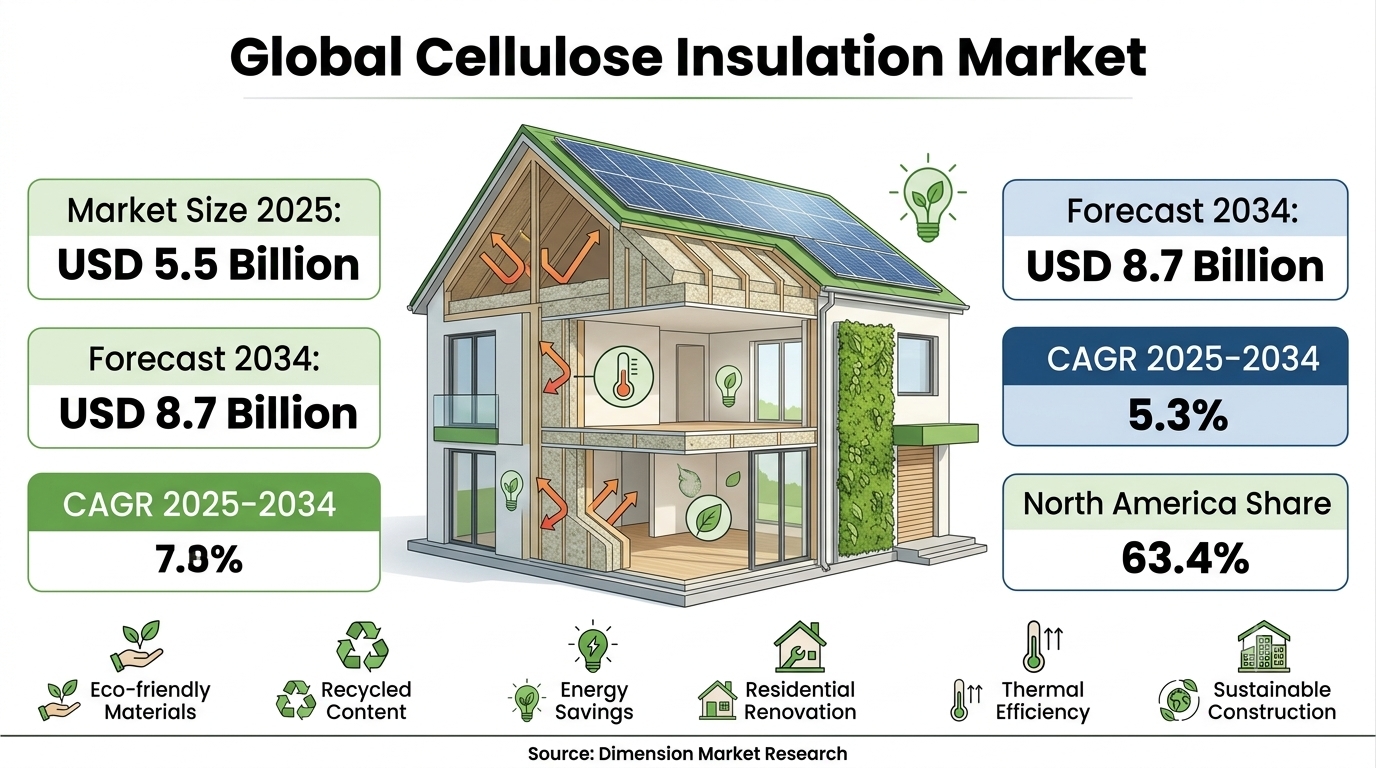
The Global Cellulose Insulation Market is gaining steady momentum as construction companies, homeowners, architects, and sustainability-focused developers increasingly adopt environmentally responsible insulation materials. Cellulose insulation, primarily manufactured from recycled paper fibers treated with fire-resistant additives, is widely used in residential, commercial, and industrial buildings to improve thermal efficiency and reduce energy consumption. The global market is expected to be valued at USD 5.5 billion in 2025 and is projected to reach USD 8.7 billion by 2034, expanding at a CAGR of 5.3% during the forecast period.
Growing emphasis on energy-efficient construction is reshaping insulation strategies worldwide. Governments and building owners are increasingly prioritizing solutions that reduce heating and cooling requirements, improve indoor thermal comfort, and support long-term sustainability objectives. Cellulose insulation benefits from these trends because of its recycled material content, effective thermal properties, sound-absorbing capabilities, and suitability for retrofit applications.
The market is also benefiting from renovation activity across aging residential and commercial buildings. Existing properties often require insulation upgrades to comply with modern energy standards or reduce utility costs. Blown-in cellulose insulation can be installed within wall cavities, attics, ceilings, and difficult-to-access areas, making it particularly suitable for renovation and energy-efficiency improvement projects.
Download a Complimentary PDF Sample Report:
https://dimensionmarketresearch.com/request-sample/cellulose-insulation-market/
Market Overview
Cellulose insulation is an environmentally oriented building insulation material generally produced from recycled newspapers, paper fibers, and other cellulose-based feedstock. These fibers are processed and treated with fire-retardant and pest-resistant compounds before being applied through loose-fill, dense-pack, or spray-based installation methods.
Its growing importance within the construction industry is closely associated with rising demand for sustainable building materials. Builders are increasingly evaluating insulation products not only on thermal resistance but also on embodied carbon, recycled content, installation flexibility, lifecycle performance, and contribution to green-building objectives.
Cellulose insulation is particularly prominent in residential construction, where attics, walls, roofs, floors, and renovation applications create recurring demand. Commercial building applications are also expanding as offices, educational institutions, healthcare facilities, retail spaces, and hospitality projects pursue stronger energy-efficiency performance.
Key Findings of the Cellulose Insulation Market
The global cellulose insulation market is projected to reach USD 5.5 billion in 2025.
The market is expected to increase to approximately USD 8.7 billion by 2034.
Global revenue is anticipated to expand at a 5.3% CAGR from 2025 to 2034.
North America is projected to account for approximately 63.4% of global market revenue in 2025.
Residential construction is expected to remain a significant demand generator due to renovation, attic insulation, and wall-cavity applications.
Sustainability requirements, building energy codes, and rising heating and cooling costs are encouraging greater use of efficient insulation materials.
Retrofit construction represents an important opportunity because cellulose can be installed in existing wall cavities without extensive structural modifications.
Market Dynamics
The cellulose insulation industry operates within a broader construction environment increasingly influenced by sustainability, energy affordability, carbon reduction, and building performance. These factors are encouraging builders to consider insulation as a strategic component of long-term energy management rather than simply a construction material.
At the same time, cellulose insulation manufacturers must address challenges related to moisture management, installation quality, fire performance perception, raw-material consistency, and competition from fiberglass, mineral wool, polyurethane foam, and other insulation technologies.
Growth is therefore closely linked to installer expertise, building regulations, local construction practices, product innovation, recycling infrastructure, and consumer understanding of cellulose-based insulation benefits.
Growth Drivers
Increasing Demand for Energy-Efficient Buildings
Energy efficiency remains one of the strongest drivers supporting the cellulose insulation market. Heating and cooling systems represent a substantial portion of building energy consumption, making effective insulation important for controlling indoor temperatures and reducing energy losses.
Cellulose insulation helps limit heat transfer through building envelopes and can improve overall building energy performance when properly installed. Rising electricity and heating costs are encouraging homeowners and commercial building operators to invest in improved insulation systems to lower long-term operating expenses.
Expansion of Green and Sustainable Construction
Sustainable construction is becoming increasingly important across both developed and emerging economies. Developers are seeking materials with lower environmental impact, higher recycled content, and reduced lifecycle carbon footprints.
Because cellulose insulation is commonly manufactured from recycled paper, it aligns strongly with circular-economy principles. Growing adoption of environmentally responsible construction standards is therefore expected to create favorable conditions for cellulose-based insulation products.
Rising Residential Renovation Activity
Renovation and retrofitting represent another major growth opportunity. Older buildings frequently contain inadequate insulation compared with modern energy-efficiency standards. Installing cellulose in attics and wall cavities can improve thermal performance without requiring complete reconstruction.
Dense-pack and blown-in applications are particularly valuable for retrofit projects because installers can fill irregular spaces, gaps, and existing cavities efficiently.
Stronger Building Energy Regulations
Building codes are increasingly emphasizing thermal efficiency and energy conservation. Requirements related to insulation performance, air sealing, building-envelope efficiency, and heating and cooling reduction are encouraging construction companies to adopt higher-performing insulation materials.
Cellulose insulation is positioned to benefit from regulatory frameworks that favor efficient and environmentally responsible building materials.
Market Trends
Growing Preference for Recycled Construction Materials
Construction companies are incorporating larger quantities of recycled and renewable materials into building projects. Cellulose insulation's recycled paper content supports sustainability objectives while helping reduce reliance on virgin raw materials.
Increasing Use of Blown-In Insulation
Blown-in installation is gaining popularity for attics, wall cavities, and retrofit projects. This installation method enables insulation material to reach irregular areas and small gaps that can be difficult to address with rigid insulation boards.
Focus on Acoustic Performance
Beyond thermal efficiency, cellulose insulation provides useful sound-dampening characteristics. Demand for quieter residential properties, offices, educational buildings, hotels, and multi-family housing is creating additional applications for insulation materials with acoustic benefits.
Integration with High-Performance Building Designs
Cellulose insulation is increasingly being considered within energy-efficient building envelopes that combine air sealing, high-performance windows, ventilation technologies, and advanced heating and cooling systems.
Challenges Affecting Market Growth
Competition from Alternative Insulation Materials
Cellulose insulation competes directly with fiberglass, mineral wool, spray polyurethane foam, expanded polystyrene, extruded polystyrene, and other insulation materials. Product selection varies according to installation costs, thermal requirements, fire performance, moisture exposure, availability, and contractor preferences.
Dependence on Proper Installation
Cellulose insulation performance can be influenced significantly by installation quality. Incorrect density, incomplete cavity filling, settling, or insufficient moisture management can reduce expected thermal efficiency. Professional installation and contractor expertise are therefore important market considerations.
Moisture Management Concerns
Moisture exposure can affect insulation performance if building envelopes are improperly designed or maintained. Manufacturers and installers must emphasize ventilation, waterproofing, vapor management, and correct installation practices to reduce moisture-related risks.
Awareness and Perception Issues
Some customers remain more familiar with conventional fiberglass or foam-based insulation solutions. Increasing education about cellulose insulation's thermal, environmental, acoustic, and retrofit advantages is important for expanding adoption.
Market Segmentation Overview
The cellulose insulation market can be evaluated across several important segmentation categories, including product form, application, installation type, building type, and end-use sector.
By Product Form
The market generally includes loose-fill cellulose, dense-pack cellulose, and spray-applied cellulose. Loose-fill products are widely used in attic spaces, while dense-pack cellulose is commonly installed within wall cavities. Spray-applied cellulose can be used in open-wall construction and specialized commercial applications.
By Application
Major applications include walls, attics, ceilings, roofs, floors, and other building-envelope areas. Attics and walls represent important consumption areas because reducing heat movement through these sections can significantly improve overall energy performance.
By Building Type
Demand can be classified across residential, commercial, and industrial buildings. Residential construction remains highly important due to strong renovation demand, single-family construction, multi-family housing, and increasing awareness of household energy efficiency.
Commercial opportunities include offices, schools, healthcare buildings, hospitality facilities, retail properties, warehouses, and institutional construction.
By Construction Type
Cellulose insulation serves both new construction and renovation projects. Renovation applications are particularly attractive because cellulose can often be blown into existing cavities and attic spaces with limited structural disruption.
Purchase the report for comprehensive details:
https://dimensionmarketresearch.com/checkout/cellulose-insulation-market/
Global Cellulose Insulation Market: Regional Analysis
North America is expected to dominate the global cellulose insulation market, accounting for approximately 63.4% of total global revenue in 2025. The region's strong position is supported by stringent building energy-efficiency requirements, established insulation installation networks, increasing awareness of environmentally responsible building materials, and substantial residential renovation activity.
The United States and Canada continue to prioritize improvements in building-envelope performance as property owners seek to reduce heating and cooling expenses. Renovation of older housing stock is particularly important because these properties frequently require insulation upgrades to meet current comfort and efficiency expectations.
Europe also represents an attractive market as countries continue promoting energy-efficient construction, renovation of aging building stock, and lower-carbon building materials. Sustainability-focused construction policies and demand for improved thermal efficiency support continued adoption of cellulose insulation.
Asia-Pacific presents longer-term opportunities as urbanization, construction activity, rising household incomes, and energy-efficiency awareness increase across major markets. However, cellulose insulation adoption may vary significantly according to local construction practices, availability of installers, climate conditions, and competition from conventional insulation products.
Other regions, including Latin America and the Middle East & Africa, are expected to provide selective opportunities as green construction practices expand and governments place greater emphasis on reducing building energy consumption.
Competitive Landscape
The global cellulose insulation market includes established insulation producers, specialized cellulose manufacturers, recycling-focused material companies, regional building-material suppliers, and installation service providers.
Competition is based on thermal performance, recycled content, fire resistance, moisture resistance, installation support, product availability, pricing, sustainability credentials, and contractor relationships. Manufacturers are increasingly focused on improving product consistency, developing enhanced fire-retardant formulations, reducing installation dust, and improving compatibility with modern building systems.
Regional distribution networks are also critical because insulation materials often depend heavily on contractor relationships and local construction channels. Companies that combine product supply with installation training, technical support, and building-performance guidance can strengthen their market position.
Partnerships with builders, architects, energy-efficiency contractors, and renovation specialists are expected to become increasingly important as demand shifts toward integrated building-envelope solutions.
Future Market Outlook
The outlook for the global cellulose insulation market remains positive through 2034. Revenue is forecast to increase from USD 5.5 billion in 2025 to USD 8.7 billion by 2034, reflecting steady expansion supported by sustainable construction, renovation activity, and tightening energy-performance standards.
Future growth is expected to be particularly strong in applications where environmental performance and retrofit flexibility are critical purchasing criteria. Residential renovation, energy-efficient homes, low-carbon construction, and green commercial buildings are likely to remain important opportunity areas.
Manufacturers are expected to invest further in product formulation, moisture resistance, fire performance, installation technology, and contractor education. Automation within insulation blowing equipment and improved building-performance monitoring could also enhance installation consistency.
As construction markets increasingly evaluate materials through both operational energy savings and lifecycle environmental impact, cellulose insulation is positioned to play an expanding role within sustainable building envelopes.
Frequently Asked Questions
1. What is the size of the global cellulose insulation market?
The global cellulose insulation market is expected to be valued at approximately USD 5.5 billion in 2025 and is projected to reach about USD 8.7 billion by 2034.
2. What is the expected CAGR of the cellulose insulation market?
The global market is anticipated to expand at a compound annual growth rate of approximately 5.3% from 2025 to 2034.
3. Which region leads the global cellulose insulation market?
North America is projected to lead the market with approximately 63.4% of global revenue in 2025, supported by building energy regulations, renovation activity, and demand for sustainable insulation materials.
4. What factors are driving demand for cellulose insulation?
Major drivers include energy-efficient construction, green-building adoption, residential renovation, recycled material usage, building-energy regulations, rising utility costs, and growing environmental awareness.
5. Where is cellulose insulation commonly used?
Cellulose insulation is commonly installed in attics, walls, ceilings, roofs, floors, and building cavities across residential, commercial, and selected industrial buildings.
Summary of Key Insights
The global cellulose insulation market is transitioning from a specialized sustainable construction segment into an increasingly important component of energy-efficient building design. With the market expected to grow from USD 5.5 billion in 2025 to USD 8.7 billion by 2034 at a CAGR of 5.3%, demand is being supported by renovation activity, energy-efficiency requirements, green construction, and increasing use of recycled building materials.
North America is expected to remain the leading regional market with approximately 63.4% revenue share in 2025, while Europe and Asia-Pacific provide additional expansion opportunities. Continued product innovation, contractor training, improved installation practices, stronger moisture management, and growing integration with high-performance building systems are likely to shape the next phase of development in the Global Cellulose Insulation Market.