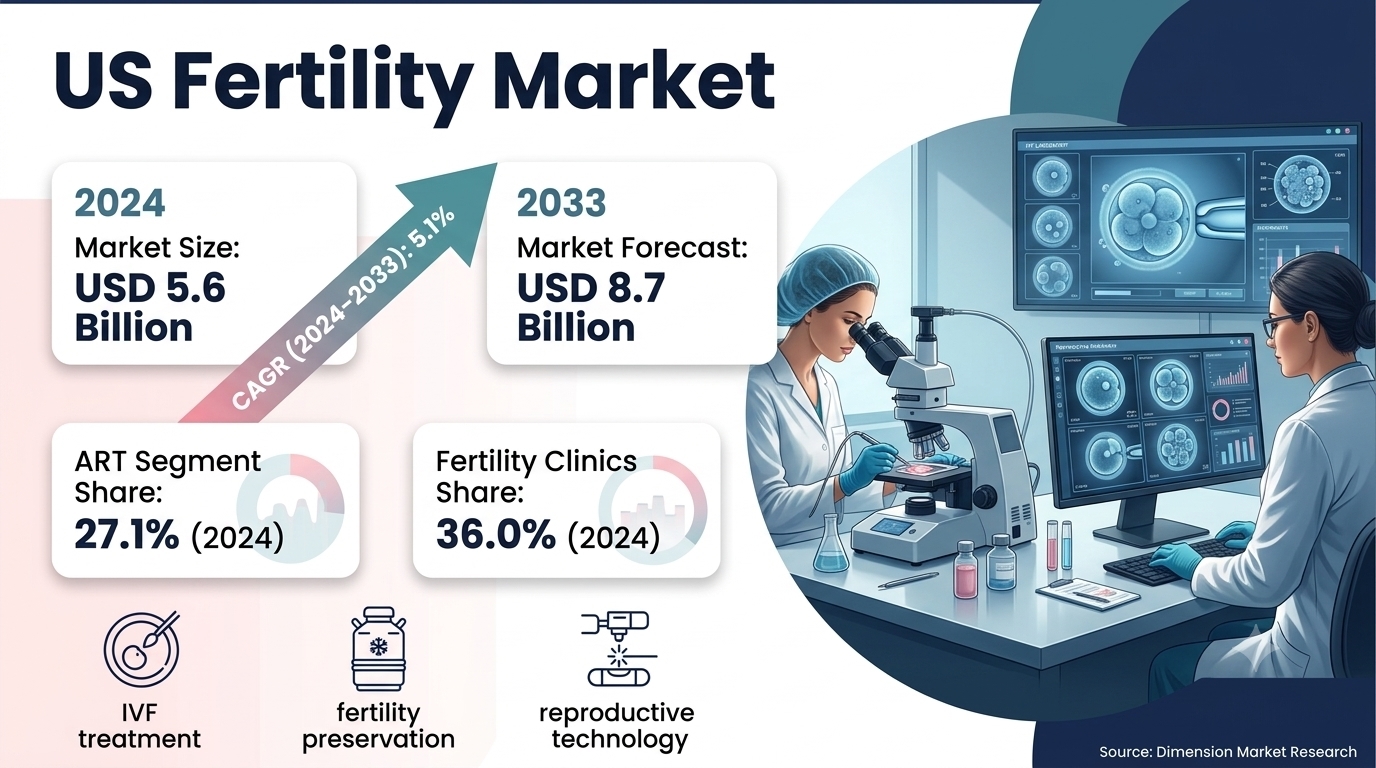
The US Fertility Market is experiencing significant transformation as reproductive healthcare becomes increasingly accessible, technologically advanced, and integrated into mainstream medical services. Growing awareness of infertility, delayed parenthood, changing family-planning preferences, and rising demand for assisted reproductive technologies are contributing to market expansion. The market is projected to reach USD 5.6 billion in 2024 and USD 8.7 billion by 2033, expanding at a CAGR of 5.1% during the forecast period.
Fertility treatments are becoming an important component of modern healthcare as individuals and couples increasingly seek medical assistance to address reproductive challenges. Advanced procedures such as in vitro fertilization (IVF), intrauterine insemination (IUI), fertility preservation, and ovulation induction are expanding available treatment options. Improvements in laboratory capabilities, diagnostic techniques, and personalized reproductive care are supporting the development of specialized fertility services throughout the United States.
The increasing adoption of reproductive technologies also reflects evolving social and demographic patterns. More individuals are choosing to delay parenthood while pursuing education, professional opportunities, and financial stability. Meanwhile, fertility clinics are expanding their capabilities through advanced embryo assessment, cryopreservation, genetic testing, and digital patient management. These developments are creating long-term opportunities for healthcare providers, pharmaceutical manufacturers, fertility specialists, and reproductive technology companies.
📄 Looking for Specific Data? Get a Free Customized Sample:
https://dimensionmarketresearch.com/request-sample/us-fertility-market/
US Fertility Market Overview
The US fertility industry encompasses medical treatments, technologies, medications, and specialized healthcare services designed to support conception and reproductive planning. The market includes assisted reproductive technology, artificial insemination, fertility preservation, fertility drugs, surrogacy services, and ovulation induction.
Demand is increasingly influenced by reproductive health awareness, treatment accessibility, and improvements in clinical outcomes. Fertility service providers are investing in sophisticated laboratory infrastructure, personalized treatment protocols, and advanced reproductive diagnostics to address diverse patient needs.
The expanding role of fertility clinics is particularly important because these facilities provide integrated diagnostic, counseling, laboratory, and treatment services. Their specialized infrastructure supports complex reproductive procedures while helping patients navigate increasingly personalized treatment pathways.
Key Market Statistics
● 2024 Market Size: USD 5.6 billion
● 2033 Market Forecast: USD 8.7 billion
● Projected CAGR: 5.1% from 2024 to 2033
● Leading Offering: ART, with over 27.1% market share in 2024
● Leading End User: Fertility clinics, with 36.0% share in 2024
● Growth Opportunity: Advanced IVF and fertility preservation services
Key Findings of the US Fertility Market
The fertility market demonstrates substantial opportunities across reproductive technologies, clinical service delivery, and fertility preservation. Increasing acceptance of medical fertility assistance is encouraging healthcare providers to improve treatment availability and patient experiences.
The expansion of specialized fertility networks is also reshaping competition. Providers with established laboratory capabilities, experienced reproductive specialists, and comprehensive treatment portfolios are positioned to capture growing patient demand.
Major Market Highlights
● IVF remains a major component of assisted reproductive services.
● Fertility clinics lead the end-user segment.
● Egg freezing supports growing fertility preservation demand.
● Genetic testing strengthens reproductive treatment planning.
● Personalized protocols improve treatment decision-making.
● Digital consultations enhance patient access and engagement.
US Fertility Market Dynamics
Growth Drivers
Rising Infertility Awareness and Delayed Parenthood
Increasing awareness of infertility and reproductive health conditions is an important driver of fertility treatment demand. Delayed childbearing can create additional reproductive challenges because fertility generally declines with age, particularly among women approaching their late thirties and forties.
As more individuals plan pregnancies later in life, demand for fertility assessments, ovarian reserve testing, IVF procedures, and fertility preservation services is expected to strengthen. Educational initiatives and greater openness about reproductive difficulties are also encouraging earlier medical consultations.
Technological Advancements in Reproductive Medicine
Advancements in embryo culture, cryopreservation, laboratory automation, and reproductive diagnostics are improving the capabilities of fertility service providers. Modern IVF laboratories use carefully controlled environments and monitoring technologies to support embryo development.
Artificial intelligence is also being explored for embryo image assessment and laboratory workflow optimization. Although clinical effectiveness varies across applications, these tools offer opportunities to support more consistent laboratory decision-making.
Important Growth Factors
● Greater awareness of reproductive health conditions
● Increasing demand for IVF and IUI procedures
● Growing adoption of egg and embryo freezing
● Expansion of specialized fertility clinics
US Fertility Market Trends
Increasing Demand for Fertility Preservation
Fertility preservation is becoming an increasingly important service category as individuals seek greater flexibility in reproductive planning. Egg freezing, sperm freezing, and embryo cryopreservation offer options for patients who wish to preserve reproductive potential for future use.
These services are relevant for individuals postponing parenthood and patients undergoing certain medical treatments that may affect fertility. Continued improvements in freezing technologies and storage infrastructure are supporting service development, although preservation does not guarantee a future pregnancy.
Personalized Fertility Treatment Approaches
Fertility providers are increasingly adopting individualized treatment strategies based on age, reproductive history, hormone levels, ovarian reserve, and underlying medical conditions.
Personalized treatment planning helps clinicians select suitable medications, laboratory procedures, and reproductive interventions. This approach may improve patient experience while supporting more informed decisions regarding treatment alternatives.
Emerging Industry Trends
● Increased investment in fertility preservation infrastructure
● Growing interest in AI-assisted embryo assessment
● Expansion of telehealth-enabled fertility consultations
● Greater emphasis on treatment transparency and counseling
US Fertility Market Challenges
High Treatment Costs and Limited Insurance Coverage
The financial burden associated with fertility treatment remains a substantial market restraint. IVF procedures may require multiple clinical visits, diagnostic examinations, medications, laboratory procedures, and embryo storage services.
Costs can increase further when patients require repeated treatment cycles or additional reproductive interventions. Insurance coverage varies across states, employers, and health plans, creating differences in affordability.
Limited financial accessibility may discourage treatment initiation or prevent patients from completing recommended procedures.
Clinical Uncertainty and Emotional Burden
Fertility treatment outcomes depend on several factors, including patient age, reproductive diagnosis, embryo characteristics, and treatment history. Not every procedure results in a successful pregnancy, creating financial and emotional uncertainty.
Patients may also experience treatment fatigue, stress, and complex reproductive decisions. Therefore, counseling services, transparent communication, and individualized clinical guidance remain essential components of comprehensive fertility care.
Major Industry Challenges
● High out-of-pocket treatment expenditure
● Uneven insurance coverage across states
● Variable treatment success rates
● Limited specialist access in underserved locations
US Fertility Market Segmentation Overview
The market is segmented by offering and end user, reflecting the diverse technologies and healthcare settings involved in reproductive treatment.
By Offering
Assisted Reproductive Technology (ART)
Assisted reproductive technology is expected to dominate the offering segment, accounting for over 27.1% of total market revenue in 2024.
ART includes procedures involving the handling of eggs or embryos, particularly IVF and intracytoplasmic sperm injection (ICSI). These procedures help address different forms of infertility and are supported by specialized embryology laboratories.
Other Fertility Treatment Categories
● IVF: Laboratory fertilization followed by embryo transfer
● ICSI: Direct injection of sperm into an egg
● AI/IUI: Placement of prepared sperm into the reproductive tract
● Fertility Preservation: Freezing eggs, sperm, or embryos
● Fertility Drugs: Medications supporting reproductive treatment
● Surrogacy: Gestational carrier arrangements where legally permitted
● Ovulation Induction: Medication-assisted ovulation stimulation
Fertility drugs and ovulation induction provide additional treatment pathways, particularly for selected patients who may not require immediate IVF intervention. Meanwhile, preservation technologies support patients pursuing longer-term reproductive planning.
By End User
Fertility clinics represent the largest end-user category, accounting for approximately 36.0% of the market in 2024.
Their leadership reflects access to reproductive endocrinologists, embryologists, specialized equipment, and integrated patient services. Dedicated clinics can coordinate diagnosis, treatment planning, egg retrieval, embryo culture, and follow-up care within comprehensive clinical environments.
Other end-user categories include:
● Hospitals: Broader reproductive healthcare and specialist services
● Surgical Centers: Procedure-focused reproductive interventions
● Research Institutions: Fertility innovation and clinical research
Competitive Landscape of the US Fertility Market
The US fertility industry features specialized reproductive healthcare providers, established fertility networks, and technology-driven treatment centers. Competition is shaped by clinical expertise, laboratory capabilities, geographic accessibility, patient experience, and treatment affordability.
Major fertility organizations are strengthening their market positions through clinic expansion, advanced reproductive technologies, specialist recruitment, and partnerships. Providers are also focusing on patient-centered services, financial counseling, and comprehensive fertility treatment packages.
Key Companies Operating in the Market
● Boston IVF
● Shady Grove Fertility
● Colorado Center for Reproductive Medicine (CCRM)
● Prelude Fertility
● Reproductive Medicine Associates (RMA)
● Kindbody
● New Hope Fertility Center
● Inception Fertility
● Extend Fertility
● Pacific Fertility Center
Competitive differentiation increasingly depends on evidence-based clinical practices, transparent outcomes reporting, convenient patient access, and advanced laboratory quality standards.
📄 Purchase the Report for Comprehensive Details:
https://dimensionmarketresearch.com/checkout/us-fertility-market/
Regional Analysis of the US Fertility Market
Northeast United States
The Northeast represents an important fertility services region, supported by established healthcare infrastructure, academic medical institutions, and specialized reproductive centers. Metropolitan markets such as New York and Boston offer extensive fertility treatment capabilities and access to experienced reproductive specialists.
Western United States
The Western region, particularly California, benefits from a developed reproductive healthcare ecosystem and strong interest in fertility preservation services. Technology adoption, specialized fertility networks, and growing awareness of reproductive options contribute to regional market development.
Southern United States
The Southern region offers opportunities for fertility clinic expansion as metropolitan populations grow and reproductive healthcare demand increases. Texas and Florida are notable markets where healthcare investment, population growth, and specialized treatment services support industry development.
Midwestern United States
The Midwest includes established fertility centers serving both metropolitan and surrounding communities. Expansion into underserved locations, greater patient education, and improved access to reproductive specialists could support future growth.
Regional demand differs according to demographic patterns, provider availability, treatment affordability, and applicable insurance requirements. Accordingly, these geographic observations should be viewed as qualitative market characteristics rather than quantified regional market-share rankings.
Future Market Outlook: 2024–2033
The US fertility market is projected to increase from USD 5.6 billion in 2024 to USD 8.7 billion by 2033, supported by rising demand for advanced reproductive healthcare and continued technological progress.
Over the forecast period, fertility service providers are expected to prioritize treatment accessibility, laboratory modernization, personalized clinical protocols, and patient engagement. Improvements in cryopreservation and reproductive diagnostics may further expand treatment options.
Future Growth Opportunities
● Expansion of IVF facilities and specialized laboratories
● Increased accessibility through employer fertility benefits
● Growing adoption of fertility preservation services
● Integration of digital tools into clinical workflows
● Greater investment in patient-centered reproductive healthcare
Despite promising opportunities, market expansion will remain dependent on healthcare affordability, regulatory requirements, clinical evidence, and the availability of skilled reproductive specialists.
Frequently Asked Questions (FAQs)
1. What is the US fertility market size in 2024?
The US fertility market is estimated at USD 5.6 billion in 2024, reflecting demand for assisted reproductive technologies, fertility medications, preservation services, and specialized reproductive healthcare.
2. What will the US fertility market be worth by 2033?
The market is projected to reach USD 8.7 billion by 2033, growing at a compound annual growth rate of 5.1% from 2024 to 2033.
3. Which treatment segment dominates the US fertility market?
Assisted reproductive technology leads the offering segment, with more than 27.1% market share in 2024. IVF and related laboratory-based reproductive procedures contribute significantly to this category.
4. What factors are driving growth in the US fertility market?
Major growth factors include delayed parenthood, greater infertility awareness, technological improvements, increasing fertility preservation demand, and expansion of specialized fertility services.
5. Which end-user segment holds the largest market share?
Fertility clinics dominate the end-user segment, accounting for approximately 36.0% of the market in 2024, supported by specialized infrastructure and comprehensive reproductive treatment capabilities.
Summary of Key Insights
The US fertility market is undergoing sustained expansion as reproductive healthcare becomes more technologically advanced and increasingly integrated into family-planning decisions. Growing demand for IVF, fertility preservation, reproductive diagnostics, and personalized treatment is creating opportunities across healthcare services and medical technologies.
With an estimated market value of USD 5.6 billion in 2024 and a projected USD 8.7 billion by 2033, the industry presents opportunities for fertility clinics, pharmaceutical companies, reproductive specialists, and healthcare investors.
Key Takeaways
● The market is forecast to grow at a 5.1% CAGR through 2033.
● ART leads the offering segment with over 27.1% share.
● Fertility clinics hold approximately 36.0% end-user share.
● Fertility preservation is an important emerging growth opportunity.
● Treatment affordability remains a major market challenge.
● Technology and personalized care will shape future competition.
Ultimately, the industry's long-term development will depend on balancing technological innovation with affordable, accessible, and evidence-based fertility care. Providers that improve patient experiences, maintain strong clinical standards, and expand responsible treatment access will be well positioned to participate in the evolving US fertility healthcare landscape.
Related Reports:
https://dimensionmarketresearch.com/report/assisted-reproductive-technology-market/
https://dimensionmarketresearch.com/report/fertility-and-pregnancy-rapid-test-kits-market/
https://dimensionmarketresearch.com/report/fertility-treatment-market/