India Pet Food Market Outlook
The market is growing as pet humanization, rising urban pet ownership, and growing awareness of scientifically formulated nutrition reshape how Indian households feed their companion animals. A fast-expanding e-commerce and direct-to-consumer ecosystem is making branded and premium products easier to find and buy across the country.
As owners shift from home-cooked meals toward packaged dry food, wet food, treats, and functional diets, the industry is evolving from a basic staples business into a nutrition-led, premiumizing category. Veterinary recommendations, new product formats, and strong investor interest in pet care startups are reinforcing this transformation, contributing to the increasing pet food market size in India.
Market Snapshot
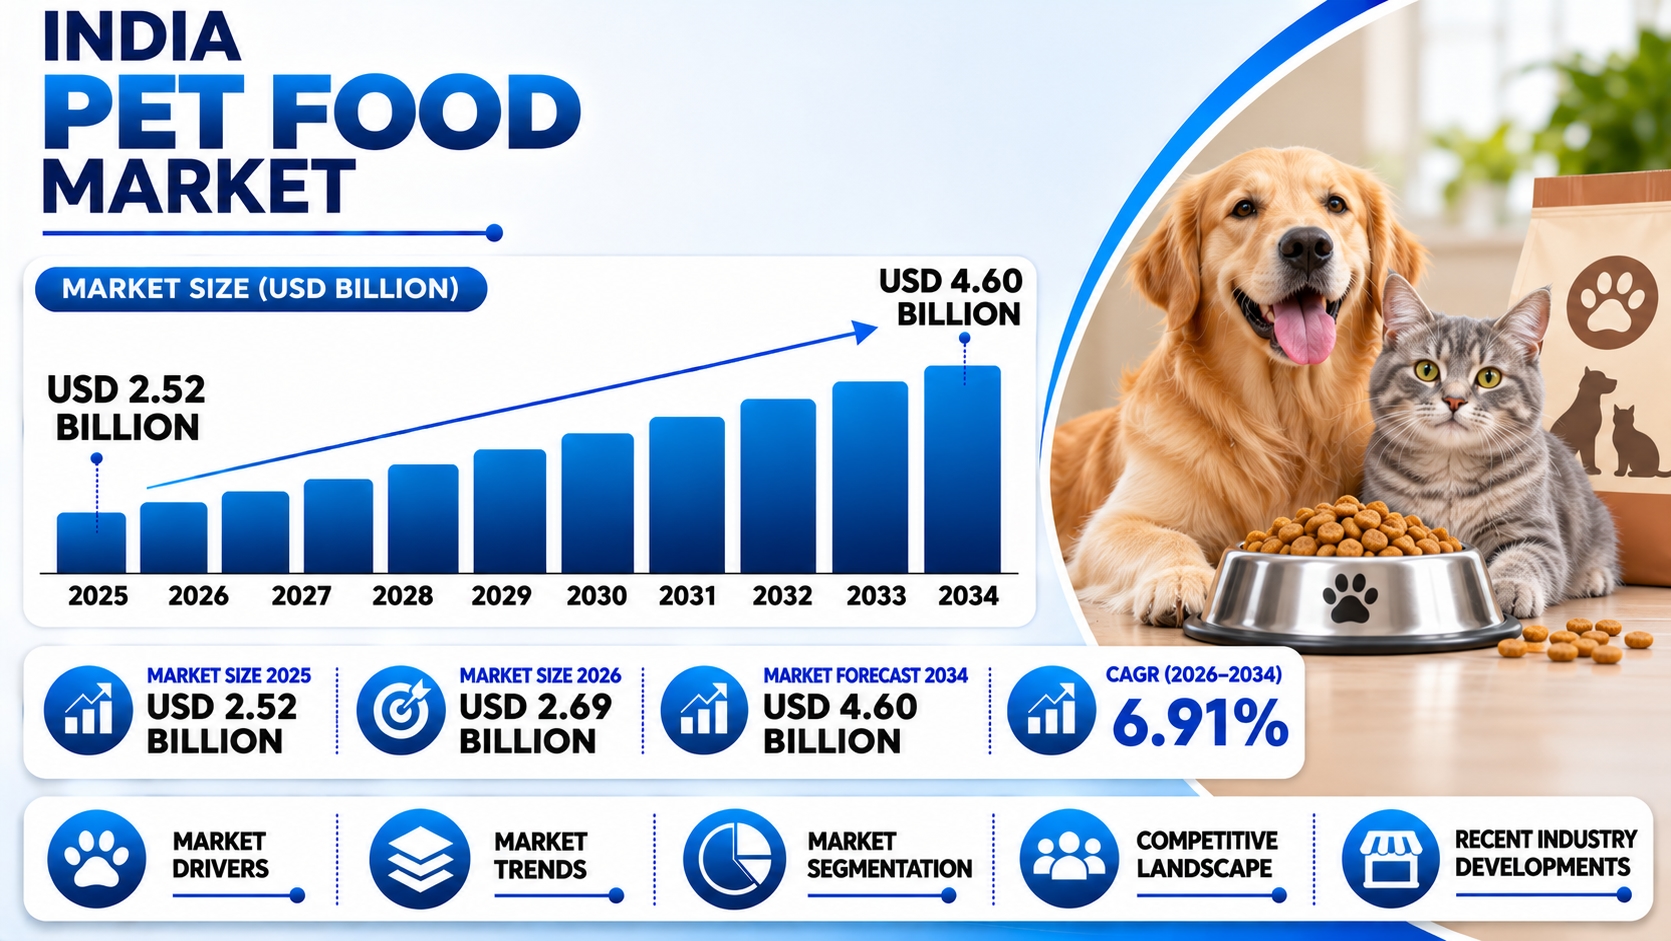
Market Size (2025): USD 2.52 Billion
Market Size (2026): USD 2.69 Billion
Forecast Market Size (2034): USD 4.60 Billion
CAGR (2026–2034): 6.91%
Leading Pet Type: Dog Food — 85.6% share (2025)
Leading Product Type: Dry Pet Food — 89.6% share (2025)
Leading Pricing Type: Mass Products — 70.0% share (2025)
Leading Ingredient Type: Animal-Derived — 80.0% share (2025)
Leading Distribution Channel: Specialty Stores — 50.0% share (2025)
Leading Region: North India — 35.0% share (2025)
Fastest Growing Region: South India
Key Growth Drivers: Pet humanization, urban pet ownership, e-commerce growth, veterinary nutrition recommendations
India Pet Food Market Key Drivers
Rising Pet Humanization and Premiumization:
Urban pet owners increasingly treat pets as family, driving demand for human-grade ingredients, grain-free diets, and breed-specific nutrition. The Indian pet care market crossed USD 3.6 Billion in 2024, with pet food as its largest category.
Expanding Urban Middle-Class Pet Ownership:
The World Bank projects India’s urban population will reach 600 million by 2036, 40% of the total population. First-generation urban households are adopting pets at an accelerating rate, and social media communities are normalizing commercial pet food over home-cooked meals.
E-Commerce and D2C Platform Growth:
Online pet food sales are expected to grow at approximately 40%+ CAGR between 2026 and 2034. Subscription-based delivery is extending repeat purchase frequency and widening brand reach.
Veterinary Nutrition Recommendation Growth:
India’s 87,000 registered veterinarians increasingly recommend prescription and therapeutic diets for diabetes, kidney disease, obesity, and allergies, creating durable brand loyalty beyond the initial prescription period.
Evaluate Market Opportunity with the Business Sample Report
India Pet Food Market Emerging Trends
Super-Premium and Functional Pet Food Adoption:
Owners increasingly seek products with functional, health-related claims such as “natural” and “high protein,” mirroring human nutrition trends and reflecting a preference for preventive care. This shift toward premium and specialized nutrition is influencing the Indian pet food market size and encouraging product innovation.
Funding for Indian Pet Food Startups:
Zoomies raised around INR 50 million (about USD 550,000) in pre-seed funding to scale its clean-label, direct-to-consumer pet food brand for cats and dogs.
Cat Food Market Acceleration:
In April 2026, Royal Canin introduced Fussy Cat, a dry food with approximately 40% protein and enhanced palatability for selective eaters, available through pet stores, online platforms, and veterinary clinics.
Veterinary Channel and Prescription Diet Expansion:
In January 2024, Hill’s Pet Nutrition announced new and upgraded Prescription Diet products for cats and dogs. Vet-recommended nutrition accounts for 28% of premium segment purchases.
India Pet Food Market Challenges
Despite robust momentum, the India pet food market faces persistent structural headwinds:
An estimated 60–70% of pet-owning households still feed home-cooked food as primary nutrition, making cultural preference the main conversion barrier for commercial brands
India’s 6.65 lakh rural villages have near-zero organized pet food penetration, limiting addressable demand to urban geographies
FSSAI regulations, BIS certification requirements, and state-level licensing for prescription diets create compliance costs that weigh on small domestic manufacturers
Wet and canned food needs refrigerated distribution that is limited outside major metros, constraining that segment at 6.4% of the market
Explore the Full Report with Charts, Table of Contents, and List of Figures
India Pet Food Market Segment Insights
By Pet Type
Dog Food — 85.6%
Cat Food — 10.4% (fastest-growing at ~8.2% CAGR)
Others — 4.0%
By Product Type
Dry Pet Food — 89.6%
Wet and Canned Pet Food — 6.4%
Snacks and Treats — 4.0% (fastest-growing at ~9.2% CAGR)
By Pricing Type
Mass Products — 70.0%
Premium Products
By Ingredient Type
Animal-Derived — 80.0%
Plant-Derived
By Distribution Channel
Specialty Stores — 50.0%
Supermarkets and Hypermarkets
Online Stores
Others
Regional Insights
North India — Share (2025): 35.0%
South India — Share (2025): 27.0%
West & Central India — Share (2025): 23.0%
East India — Share (2025): 15.0%
Competitive Landscape
India’s pet food market exhibits moderate concentration, with Mars, Incorporated, Nestlé S.A., and Colgate-Palmolive Company collectively holding approximately 55–65% of organized market revenue in 2025. Domestic brands led by IB Group capture 20–25% of mid-tier volumes through competitive pricing and India-specific e-commerce strategies.
Mars, Incorporated — Brand / Platform: Pedigree, Whiskas, Sheba, Cesar, Iams, Royal Canin
Core Strength: Broadest brand portfolio; largest distribution network; R&D and vet nutrition expertise across pet categories
Nestlé S.A. — Brand / Platform: Felix, Purina Friskies, Purina ProPlan
Core Strength: Premium and science-backed formulations; strong modern trade presence; growing e-commerce channel
Colgate-Palmolive Company — Brand / Platform: Hill’s Science Diet, Hill’s Prescription Diet
Core Strength: Vet-channel dominance; therapeutic prescription diet leadership
IB Group — Brand / Platform: Drools
Core Strength: Largest Indian-origin brand; cost-competitive with premium positioning; strong D2C and e-commerce scaling across Tier 1–2 cities
Farmina Pet Foods — Brand / Platform: Farmina Vet Life, N&D
Core Strength: Super-premium natural ingredient positioning; growing adoption among health-conscious urban pet owners
Recent Developments
April 2026 — Drools Pet Food announced an INR 180 crore investment and a partnership with Tetra Pak to launch fresh pet food in Tetra Recart aseptic packaging, making it shelf-stable without refrigeration
April 2026 — Royal Canin introduced Fussy Cat, a high-protein dry food in India formulated for selective cat eaters
July 2025 — Mars rolled out its “Feed Them Like Cats and Dogs” campaign for Pedigree and Whiskas to educate owners on the different nutritional needs of dogs and cats
Investment Opportunities
Fastest Growing Segments: Cat food (~8.2% CAGR), snacks and treats (~9.2%), wet and canned pet food (~8.5%), and super-premium dry food (~11%) are the highest-return investment vectors through 2034, addressing an incremental market of approximately USD 1.2 Billion by 2034 above 2025 spend.
Emerging Market Expansion: Tier-2 cities such as Jaipur, Lucknow, Pune, Bhopal, and Coimbatore represent an under-penetrated INR 800 crore pet food opportunity by 2030, with Tier-2 e-commerce growing at approximately 55% annually.
Venture & Institutional Investment: India’s pet care sector attracted USD 100+ Million in venture capital in 2023–2025, with pet food accounting for 40–50% of deployment. Contract manufacturing is also lowering entry barriers for global brands.
Discuss Your Requirements With an Analyst and Get Your Customized Market Report
Frequently Asked Questions (FAQ)
What is the current size of the India pet food market?
The India pet food market is estimated at USD 2.69 Billion in 2026 and is forecast to reach USD 4.60 Billion by 2034 at a 6.91% CAGR.
Which pet type leads the market?
Dog food leads with an 85.6% share in 2025, supported by an estimated 31–37 million pet dogs and decades of branded nutrition awareness.
Which product type leads the market?
Dry pet food dominates with an 89.6% share in 2025, reflecting its storage advantages, price competitiveness, and appeal to first-time pet owners.
Which region dominates?
North India leads with a 35.0% share in 2025, anchored by Delhi-NCR’s premium pet ownership concentration, veterinary infrastructure, and organized pet retail network.
Who are the leading companies?
Key players include Mars, Incorporated, Nestlé S.A., Colgate-Palmolive Company, IB Group, and Farmina Pet Foods.
Conclusion
The India pet food market is a compelling consumer growth story, driven by pet humanization, urban pet ownership, and a structural shift from home-cooked to commercial nutrition. The pet food industry in India is moving steadily toward premium, functional, and digitally distributed products.
Three forces will shape the market through 2034: cat food and treats outpacing the overall market, e-commerce and D2C extending reach into Tier-2 cities, and veterinary-led nutrition deepening brand loyalty. Companies that invest in product innovation, omnichannel distribution, and consumer education will be best placed to capture the USD 2.08 Billion of incremental value ahead.
Source: IMARC Group