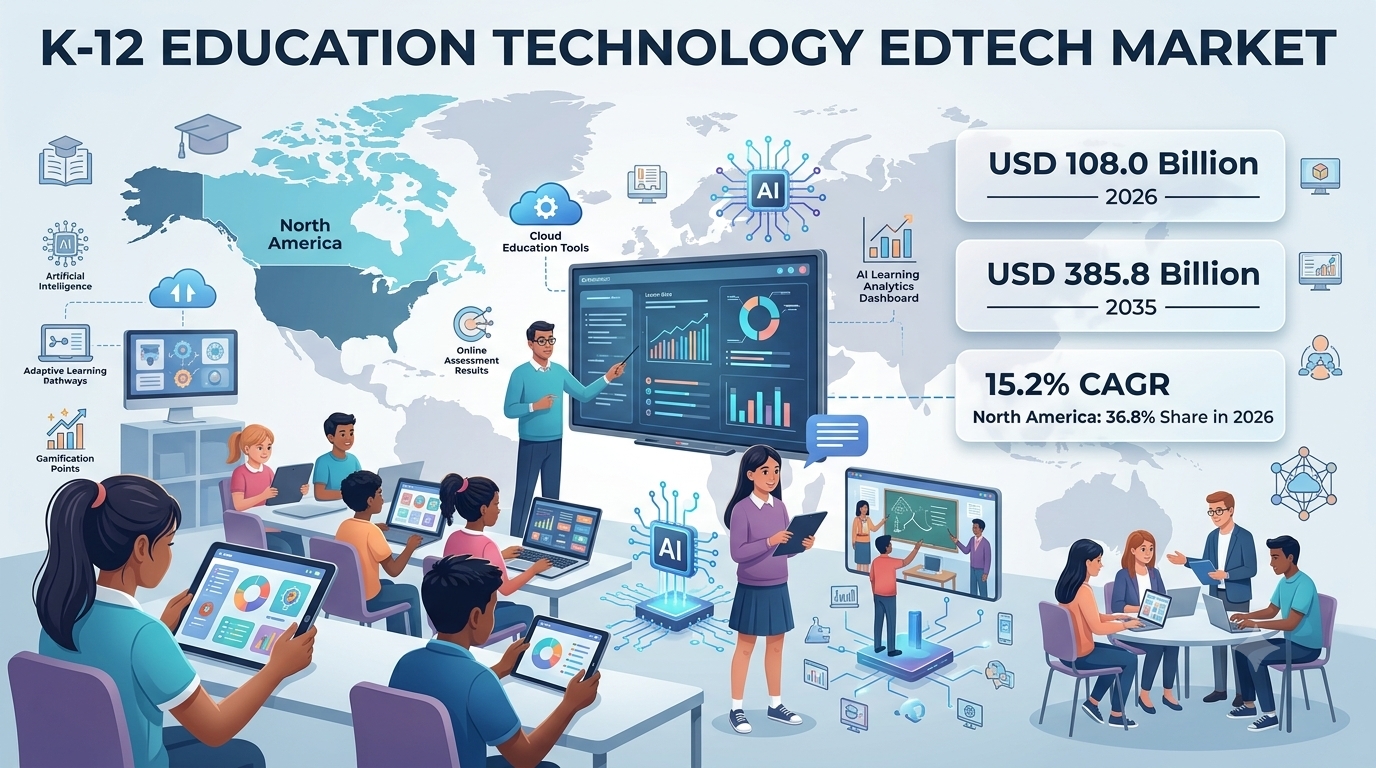
The Global K 12 Education Technology Edtech Market is undergoing rapid transformation as schools, teachers, students, and education authorities increasingly adopt digital platforms, artificial intelligence, cloud-based learning systems, virtual classrooms, assessment technologies, and personalized learning solutions. The market is projected to reach USD 108.0 billion in 2026 and expand to USD 385.8 billion by 2035, registering a strong compound annual growth rate of 15.2% during the forecast period.
Digital transformation within primary and secondary education is moving beyond basic classroom technology toward integrated learning ecosystems. Schools are increasingly combining learning management systems, interactive content, digital assessments, communication platforms, student information systems, and analytics tools. Growing internet penetration and expanding device availability are helping educational institutions provide flexible access to learning materials while improving collaboration between teachers, students, and parents.
Artificial intelligence is also reshaping K-12 education by enabling adaptive learning, automated assessment, intelligent tutoring, content recommendations, and real-time performance tracking. These technologies support educators by identifying learning gaps and allowing instruction to be customized according to individual student requirements. As schools increasingly prioritize measurable learning outcomes and personalized education, demand for advanced EdTech platforms is expected to strengthen considerably.
Download a Complimentary PDF Sample Report:
https://dimensionmarketresearch.com/request-sample/k-12-education-technology-edtech-market/
Market Overview
The K 12 Education Technology Edtech Market includes digital technologies, software platforms, educational content, hardware solutions, and technology-enabled services developed for students and educators from kindergarten through grade 12. These solutions improve teaching efficiency, classroom engagement, learning accessibility, academic performance, assessment capabilities, and administrative processes.
Technology is becoming increasingly integrated into both classroom-based and remote education. Traditional teaching models are evolving toward blended learning environments in which physical instruction is supported by digital content, online assessments, collaborative applications, interactive displays, and cloud-based learning platforms.
The expected increase from USD 108.0 billion in 2026 to USD 385.8 billion by 2035 reflects the increasing strategic importance of educational technology. Schools are investing not only in devices but also in scalable software ecosystems that can support curriculum management, communication, data analytics, digital content distribution, and personalized student development.
Growing demand for learning continuity, digital literacy, accessibility tools, multilingual educational content, and skills-based education further supports market expansion. Education providers are also focusing on technologies that simplify teacher workflows while creating more engaging and individualized student experiences.
Key Findings
The global market is projected to reach USD 108.0 billion in 2026.
Market revenue is forecast to increase to approximately USD 385.8 billion by 2035.
The market is expected to grow at a 15.2% CAGR from 2026 to 2035.
North America is projected to account for 36.8% of global revenue in 2026.
AI-powered adaptive learning and personalized education platforms are becoming important areas of innovation.
Cloud-based learning platforms are supporting scalable implementation across schools and education networks.
Digital assessments and learning analytics are gaining importance as educators seek measurable academic outcomes.
Blended learning continues to expand as schools combine classroom instruction with digital resources and collaborative technologies.
Market Dynamics
The K 12 Education Technology Edtech Market is influenced by technological innovation, education policy, infrastructure availability, institutional budgets, teacher readiness, student accessibility, and changing learning expectations.
Education authorities increasingly view technology as a long-term component of modern learning rather than as supplementary infrastructure. Digital systems are being integrated into curriculum delivery, assessment, administration, communication, and student support.
At the same time, the market faces implementation challenges. Schools must manage data privacy, cybersecurity, teacher training, technology integration, connectivity limitations, device availability, and ongoing software costs. Vendors that provide secure, interoperable, user-friendly, and scalable solutions are consequently positioned to address significant institutional requirements.
Major Market Trends
AI-Powered Personalized Learning
Artificial intelligence is becoming one of the most influential trends across K-12 education. AI-enabled systems can analyze student behavior, academic performance, response patterns, and learning progress to recommend personalized lessons and activities.
Adaptive platforms allow students to progress at different speeds while providing teachers with insights into areas requiring additional instruction. Generative AI is also creating opportunities for lesson preparation, practice exercises, tutoring assistance, content development, and administrative automation.
Growing Adoption of Cloud-Based Education
Cloud technology enables schools to deploy learning platforms without maintaining extensive local information technology infrastructure. Cloud-based applications provide centralized access to educational resources, assignments, assessments, communication tools, and student performance information.
The scalability of cloud infrastructure is particularly valuable for large school networks because administrators can manage users, content, and applications across multiple locations through unified environments.
Expansion of Immersive Learning
Virtual reality, augmented reality, simulations, and interactive visualization technologies are creating new approaches to experiential learning. These tools can help students understand complex scientific, mathematical, geographical, and historical concepts through interactive experiences.
While adoption remains influenced by hardware costs and institutional budgets, immersive learning is expected to become increasingly relevant as devices become more affordable and educational content improves.
Increased Focus on Learning Analytics
Education institutions are increasingly using analytics to evaluate attendance, engagement, learning progress, assessment results, and academic risks. Data-driven systems allow teachers and administrators to identify students who may require additional support.
The transition toward evidence-based education is increasing demand for platforms that combine learning management with analytics and performance dashboards.
Growth Drivers
Rising Digitalization of Schools
Governments and educational institutions are expanding digital infrastructure to improve education quality and accessibility. Interactive classrooms, tablets, laptops, digital whiteboards, learning platforms, and broadband connectivity are becoming increasingly common components of school modernization programs.
Continued investment in digital education infrastructure provides a strong foundation for long-term EdTech adoption.
Demand for Personalized Education
Traditional classroom models often provide standardized instruction to groups of students despite differences in learning speed and academic ability. EdTech platforms can address this limitation by delivering personalized content, adaptive assessments, and targeted intervention.
Personalized education can improve student engagement while helping teachers understand individual learning requirements more effectively.
Growth of Blended Learning
Blended learning combines instructor-led classroom education with online learning tools. This approach provides students with greater flexibility while allowing teachers to supplement classroom instruction using multimedia content, practice applications, digital assessments, and collaborative tools.
Schools increasingly see blended learning as a sustainable educational model rather than a temporary alternative.
Increasing Use of Digital Assessments
Digital assessment platforms simplify test administration, scoring, reporting, and performance analysis. Automated assessment systems can provide immediate feedback and enable educators to identify curriculum areas where students require additional instruction.
Digital testing also supports remote assessment and enables educational institutions to analyze large volumes of student performance data more efficiently.
Market Challenges
One of the most significant challenges is the digital divide between students with strong access to devices and high-speed internet and those with limited connectivity. Unequal technology access can restrict the effectiveness of digital learning programs, particularly in underserved communities.
Cybersecurity and student data privacy are also major concerns. Educational institutions manage sensitive personal and academic information, making secure identity management, data protection, and cybersecurity essential requirements.
Teacher preparedness represents another challenge. Even advanced educational platforms can deliver limited results if educators are not adequately trained to integrate technology into teaching practices.
Cost is also an important consideration. Schools must evaluate hardware acquisition, software subscriptions, technical support, cybersecurity, maintenance, integration, and device replacement costs when developing long-term digital education strategies.
Market Segmentation Overview
The K 12 Education Technology Edtech Market can be evaluated across several major segments based on technology, solution type, deployment, application, and end user.
By Technology
Artificial intelligence and machine learning are gaining importance as schools adopt adaptive learning, automated assessment, intelligent tutoring, and predictive analytics. Cloud computing also represents a major technology category by supporting scalable digital learning infrastructure.
Other emerging technologies include virtual reality, augmented reality, gamification, learning analytics, and collaborative digital environments.
By Solution
The market includes learning management systems, student information systems, educational content platforms, assessment solutions, classroom management applications, communication tools, digital tutoring platforms, and administration software.
Integrated platforms that combine multiple education functions are increasingly attractive because schools can reduce technological fragmentation.
By Deployment
Cloud-based deployment is expanding rapidly due to scalability, remote accessibility, simplified software updates, and lower infrastructure requirements. On-premise platforms remain relevant for institutions seeking greater control over infrastructure and information management.
By Application
Important applications include classroom learning, homework and assignments, examination and assessment, teacher development, student collaboration, administration, personalized learning, and curriculum management.
By End User
The market primarily serves public schools, private schools, school districts, education authorities, teachers, students, and parents. Technology requirements vary significantly according to institutional size, curriculum structure, budgets, technology infrastructure, and educational objectives.
Purchase the report for comprehensive details:
https://dimensionmarketresearch.com/checkout/k-12-education-technology-edtech-market/
Regional Analysis
North America Leads the Global Market
North America is projected to remain the leading region in the global K 12 Education Technology Edtech Market, accounting for approximately 36.8% of global market revenue in 2026.
The region benefits from widespread digital-learning adoption, advanced educational infrastructure, strong institutional support, significant technology investment, and high levels of internet and device penetration. Schools across the region continue to adopt cloud platforms, AI-enabled learning solutions, classroom collaboration technologies, digital assessments, and learning analytics.
The early adoption of advanced educational technologies also supports continuous innovation. Education providers increasingly focus on integrated platforms that simplify administration while improving teaching effectiveness and student engagement.
Asia-Pacific
Asia-Pacific represents a major long-term growth opportunity due to its large school-age population, rapidly expanding digital infrastructure, government-backed education modernization programs, and increasing smartphone and internet penetration.
Growing adoption of digital classrooms and online learning platforms across emerging economies is expected to increase demand for scalable and affordable EdTech solutions.
Europe
Europe continues to strengthen digital education through school technology modernization, digital curriculum initiatives, teacher training programs, and online educational resources. Strong emphasis on data privacy and responsible technology use is influencing platform development and procurement decisions.
Latin America, Middle East, and Africa
These regions present emerging opportunities as governments and private education providers invest in connectivity, online education, learning management systems, and digital classroom infrastructure. However, affordability, broadband availability, and unequal device access remain important factors influencing adoption.
Competitive Landscape
The competitive environment is characterized by established education technology companies, software providers, digital content developers, cloud technology companies, learning platform providers, and specialized startups.
Competition increasingly focuses on platform usability, personalized learning capabilities, AI functionality, content quality, cybersecurity, analytics, interoperability, and integration with existing school systems.
Companies are strengthening their market presence through product development, strategic collaborations, platform integration, acquisitions, partnerships with schools, and expansion into new geographic markets.
AI is expected to create an additional competitive dimension. Vendors capable of developing secure and reliable intelligent tutoring, automated assessment, teacher assistance, personalized learning, and predictive analytics solutions may strengthen their positions within the evolving K-12 technology ecosystem.
Future Market Outlook
The future of the K 12 Education Technology Edtech Market is expected to be shaped by increasingly intelligent, connected, personalized, and data-driven learning environments. With market revenue projected to increase from USD 108.0 billion in 2026 to USD 385.8 billion by 2035, technology adoption across education is expected to remain strong.
Artificial intelligence will likely become embedded across learning management, assessment, tutoring, content development, student support, and school administration. Instead of functioning as separate applications, advanced technologies are expected to become integrated components of broader educational ecosystems.
Interoperability will also become increasingly important. Schools often use multiple applications, creating demand for platforms capable of exchanging data securely and providing unified access to educational resources.
The market is also likely to experience increased demand for technologies that demonstrate measurable educational value. Schools and governments will increasingly evaluate solutions according to student outcomes, teacher productivity, accessibility, security, affordability, and scalability.
Frequently Asked Questions
What is the size of the Global K 12 Education Technology Edtech Market?
The Global K 12 Education Technology Edtech Market is projected to reach approximately USD 108.0 billion in 2026.
What is the expected growth rate of the market?
The market is expected to expand at a compound annual growth rate of 15.2% from 2026 to 2035.
What will the market be worth by 2035?
The global K-12 EdTech market is forecast to reach approximately USD 385.8 billion by 2035, supported by growing adoption of digital learning, AI, cloud platforms, and personalized education technologies.
Which region leads the K 12 Education Technology Edtech Market?
North America is expected to lead the market in 2026 with approximately 36.8% of global revenue, supported by advanced digital infrastructure and high adoption of educational technologies.
What are the major technologies influencing K-12 EdTech growth?
Artificial intelligence, machine learning, cloud computing, adaptive learning, learning analytics, virtual reality, augmented reality, gamification, and digital assessment technologies are among the major technologies influencing market development.
Summary of Key Insights
The Global K 12 Education Technology Edtech Market is entering a period of significant expansion as schools increasingly integrate technology into teaching, assessment, administration, and student engagement. The market is projected to rise from USD 108.0 billion in 2026 to USD 385.8 billion by 2035, representing a 15.2% CAGR.
Artificial intelligence, cloud-based platforms, adaptive learning, digital assessment, and learning analytics are expected to play increasingly important roles in the future education ecosystem. North America is projected to retain its leading position with a 36.8% market share in 2026, while Asia-Pacific and other developing regions offer substantial long-term opportunities.
Despite challenges involving infrastructure gaps, cybersecurity, data privacy, affordability, and teacher readiness, continued investment in digital education is expected to support sustained market development. As schools increasingly prioritize personalized learning and measurable academic outcomes, EdTech will become an essential component of modern K-12 education worldwide.