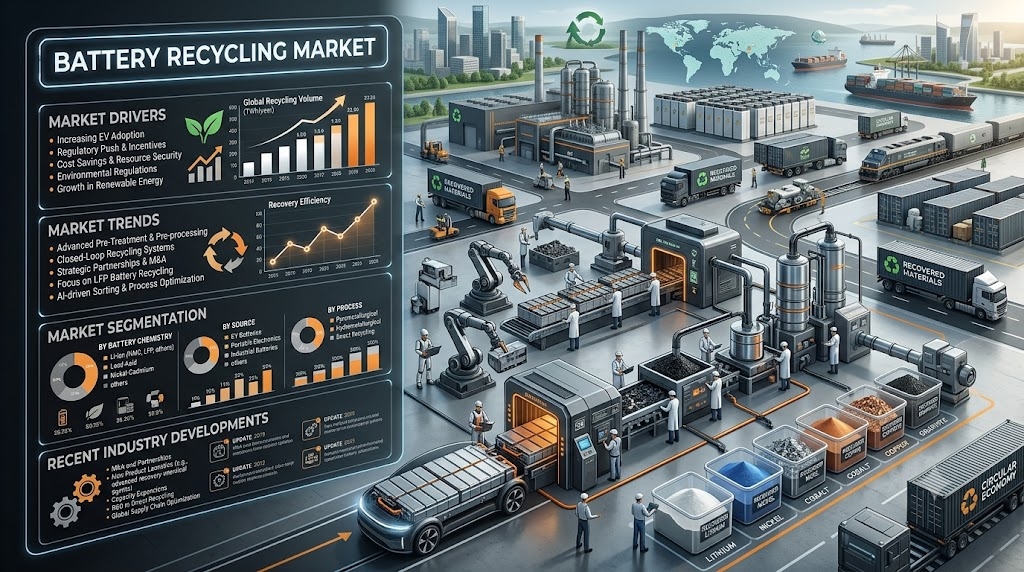
Market Overview:
According to IMARC Group’s latest research publication, “Battery Recycling Market: Global Industry Trends, Share, Size, Growth, Opportunity and Forecast 2026-2034”, The global battery recycling market size grew from USD 18.0 Billion in 2025 to USD 19.5 Billion in 2026. Looking forward, IMARC Group estimates the market to reach USD 32.9 Billion by 2034, exhibiting a CAGR of 6.74% from 2026-2034.
This detailed analysis primarily encompasses industry size, business trends, market share, key growth factors, and regional forecasts. The report offers a comprehensive overview and integrates research findings, market assessments, and data from different sources. It also includes pivotal market dynamics like drivers and challenges, while also highlighting growth opportunities, financial insights, technological improvements, emerging trends, and innovations. Besides this, the report provides regional market evaluation, along with a competitive landscape analysis.
How Technology and Policy Are Reshaping the Battery Recycling Market
Lithium-based batteries account for 40% of the battery recycling market by type, driven by their dominant use in electric vehicles, energy storage systems, and consumer electronics, with hydrometallurgical technologies now achieving recovery rates exceeding 95% for key metals such as cobalt, nickel, and manganese.
The automotive segment leads as a source with 35% market share, reflecting both the near-100% recycling rates of lead-acid batteries in developed markets and the growing wave of end-of-life lithium-ion packs from electric and hybrid vehicles.
Material extraction dominates end-use with a 42% share, as closed-loop hydrometallurgical and pyrometallurgical processes increasingly substitute recovered materials for newly mined inputs, reducing both cost and environmental impact for battery manufacturers globally.
In August 2026, China introduced the first battery recycling regulation with enforceable administrative penalties, marking a pivotal compliance inflection point as the volume of retired power batteries in the country is projected to exceed one million metric tons in 2026.
In November 2025, Clarios announced plans to fast-track the restart of its Florence, South Carolina facility as part of its USD 6 billion American Energy Manufacturing Strategy, underscoring the scale of investment directed at automotive battery recycling to secure domestic supply chains.
Download a sample PDF of this report: https://www.imarcgroup.com/battery-recycling-market/requestsample
Key Trends in the Battery Recycling Market
Growing EV Adoption Driving Demand: The surging global adoption of electric vehicles is one of the most powerful catalysts propelling demand for battery recycling solutions. Global EV car sales reached 17 million units in one year, directly accelerating the supply of recyclable batteries entering the global market. EV manufacturers design batteries for operational lives of approximately eight to ten years, meaning the first significant wave of retired large-format battery packs is now entering recycling streams at scale, creating urgent demand for infrastructure capable of recovering high-value materials such as cobalt, nickel, manganese, and lithium.
Expanding Renewable Energy Storage Systems: The rapid global transition toward renewable energy is driving significant growth in energy storage system deployments, introducing a substantial new stream of recyclable batteries. As solar and wind power installations proliferate across residential, commercial, and industrial sectors, large-format stationary battery storage solutions are reaching end-of-life, adding to the growing pipeline of recyclable battery modules. In 2025, BatX Energies Pvt. Ltd. launched its Critical Minerals Extraction facility (HUB-1) in Uttar Pradesh, India, designed to recover lithium, cobalt, nickel, and manganese from spent lithium-ion batteries, reinforcing the circular economy model for the battery storage sector.
Rising Environmental Awareness and Stricter Regulation: The improper disposal of batteries poses severe ecological risks, including hazardous chemical leaching into soil and groundwater systems. Governments globally are responding with progressively stringent mandates. In 2025, India announced plans to implement incentive programs promoting the recycling of 24 identified essential minerals, including lithium and cobalt, crucial for reducing dependence on imports of critical raw materials. China’s 2026 compliance regulation is now driving the industry’s transition from fragmented operations toward formalized, industrial-scale battery recycling practices.
Critical Mineral Recovery Becoming Strategically Central: Lithium represents the leading recovered material with a 25% market share among all materials extracted from spent batteries. The US Department of Energy announced a USD 70.8 million investment to support EV battery recycling innovations, strengthen domestic manufacturing capabilities, and advance clean energy objectives. Governments and corporations alike are prioritizing lithium recovery as part of broader critical mineral strategies as primary supply faces pressure from rapidly escalating demand.
Technological Innovation Enhancing Recovery Efficiency: Advanced hydrometallurgical, pyrometallurgical, and direct recycling processes are enabling increasingly efficient extraction of cathode materials from spent batteries. In 2025, Toray Industries revealed technology capable of recovering high-purity lithium through a newly developed high-durability, high-selectivity nanofiltration membrane. These technological strides are reducing processing costs, improving material yields, and making battery recycling commercially attractive for a wider set of operators globally.
Growth Factors in the Battery Recycling Market
EV Fleet Scale and End-of-Life Battery Volumes: The United States alone has surpassed four million electric vehicles sold, generating mounting volumes of end-of-life lithium-ion battery packs entering commercial recycling pathways. Asia-Pacific’s world-leading EV manufacturing ecosystem is generating the largest regional recycling feedstock, with China’s national producer responsibility framework structuring the domestic collection and processing system at massive scale. The scale of these battery volumes is creating sustained demand for new recycling infrastructure investments across all major regions.
Government Policy and Regulatory Frameworks: The US Inflation Reduction Act’s critical minerals provisions have catalyzed significant domestic recycling capacity investments, positioning the country as a strategic hub for closed-loop battery materials recovery. The European Union Battery Regulation sets binding requirements for recycling efficiency, recovered material content in new batteries, and producer take-back obligations, compelling automakers, battery manufacturers, and recyclers to invest in compliant collection and processing networks. Saudi Vision 2030 and the UAE’s Circular Economy Policy 2031 are similarly encouraging battery waste management investment across the Middle East and Africa region.
Circular Supply Chain Demand from Battery Manufacturers: Rising critical mineral prices and supply chain vulnerabilities are driving battery manufacturers, EV producers, and energy storage operators to formalize offtake agreements with recyclers. Partnerships such as the collaboration between Panasonic Energy’s Suminoe Factory and Sumitomo’s facilities in Japan to produce recycled-content nickel sulfate for use in cathode materials illustrate how OEM-recycler partnerships are becoming structurally integrated within battery supply chains globally.
Expansion of Recycling Infrastructure in Emerging Economies: In January 2025, Ace Green Recycling completed a lease for the site of the largest battery recycling plant in India, to be located in Mundra, Gujarat, designed to expand lithium-iron phosphate and broader lithium-ion battery recycling operations significantly. In February 2025, Mobec Innovation opened its first lithium battery recycling facility in Noida, Uttar Pradesh, with an annual processing capacity of up to 6,000 tons. These developments signal accelerating private-sector confidence in the commercial viability of battery recycling in high-growth markets.
Growing ESG Obligations and Corporate Sustainability Commitments: Increasing ESG mandates and corporate net-zero commitments are driving organizations across industries to adopt structured battery return and recycling programs. In June 2025, UK-based clean technology group Altilium announced plans to invest USD 34.69 million in its ACT 3 EV battery recycling facility in Plymouth, designed to recover cobalt, nickel, and lithium from 24,000 electric vehicles annually, with the facility scheduled to open in late 2026, reflecting the scale of private investment being directed at compliant, high-throughput battery recycling.
Leading Companies Operating in the Global Battery Recycling Industry:
Accurec Recycling GmbH
Aqua Metals
Battery Solutions
Call2Recycle Inc.
Eco-Bat Technologies
Enersys
Exide Technologies
G. & P. Batteries Limited
Gravita India Limited
Johnson Controls
Retriev Technologies Inc.
Umicore
Battery Recycling Market Report Segmentation:
Breakup By Type:
Lead-acid Batteries
Nickel-based Batteries
Lithium-based Batteries
Others
Lithium-based batteries lead the type segment with 40% market share, driven by widespread adoption in electric vehicles, consumer electronics, and energy storage systems, alongside high concentrations of commercially valuable critical minerals that make recycling both strategically important and economically attractive.
Breakup By Source:
Industrial
Automotive
Consumer Products
Electronic Appliances
Others
The automotive sector leads with 35% of the source segment, reflecting the massive scale of lead-acid batteries in conventional vehicles alongside the rapidly growing volume of lithium-ion packs from hybrid and electric vehicles reaching end-of-life.
Breakup By End-Use:
Reuse
Repackaging
Extraction
Others
Extraction dominates with 42% market share, as advanced hydrometallurgical and pyrometallurgical processes recover economically valuable materials such as lithium, cobalt, nickel, manganese, lead, and copper that are returned directly to the battery manufacturing supply chain.
Breakup By Material:
Manganese
Iron
Lithium
Nickel
Cobalt
Lead
Aluminium
Others
Lithium represents the leading recovered material with 25% share, reflecting its indispensable role in modern battery chemistry, the increasing scarcity of primary supply relative to demand, and rising commercial value of high-purity recovered lithium suitable for cathode active material production.
Breakup By Region:
North America (United States, Canada)
Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
Europe (Germany, France, United Kingdom, Italy, Spain, Russia, Others)
Latin America (Brazil, Mexico, Others)
Middle East and Africa
Asia Pacific holds the leading regional position with 34% market share, powered by the world’s largest concentration of electric vehicle manufacturing, the most extensive gigafactory infrastructure, and rapidly accumulating volumes of both lithium-ion production scrap and end-of-life battery packs across China, India, South Korea, and Japan.
Recent News and Developments in the Battery Recycling Market
August 2026: China introduced its first battery recycling regulation with enforceable administrative penalties, marking the most significant regulatory milestone in the country’s recycling sector. The theoretical volume of retired power batteries in China is projected to exceed one million metric tons in 2026, and the regulation is driving the industry’s transition from fragmented, small-scale workshops toward formalized, industrial-scale battery recycling operations, with major manufacturers such as CATL and Gotion High-Tech accelerating capacity investments in response.
October 2025: NavPrakriti commenced operations at Eastern India’s first lithium-ion battery recycling plant near Kolkata, enabling the region to process battery waste from electric vehicles, consumer electronics, and industrial uses. The launch aligns with projections that India will need to recycle more than 1.2 million electric vehicle batteries per year by 2030, a figure anticipated to rise to 14 million by 2040, as domestic lithium-ion battery demand is expected to reach 54 gigawatt hours by fiscal year 2027.
February 2025: Lithium Salvage secured £1.7 million in investment from a funding round led by Northstar Ventures to develop a lithium-ion battery waste refinery in Sunderland, UK, underscoring growing private sector commitment to building domestic battery recycling infrastructure within Europe’s increasingly policy-driven recycling landscape.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
About Us:
IMARC Group is a global management consulting firm that helps the world’s most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Contact Us:
IMARC Group
134 N 4th St. Brooklyn, NY 11249, USA
Email: sales@imarcgroup.com
Tel No: (D) +91 120 433 0800
United States: +1-201-971-6302